THE SHORT ANSWER
Seller repairs and a repair credit solve different problems. Repairs may address a condition before closing if the scope and verification are clear; a credit may give the buyer control while leaving investigation, approvals and cost uncertainty with the buyer. Compare the actual work, timing and documentation, and confirm transaction and lender constraints with the appropriate advisers. Neither option is automatically available or better for every inspection finding.
Define the condition before choosing a negotiation format
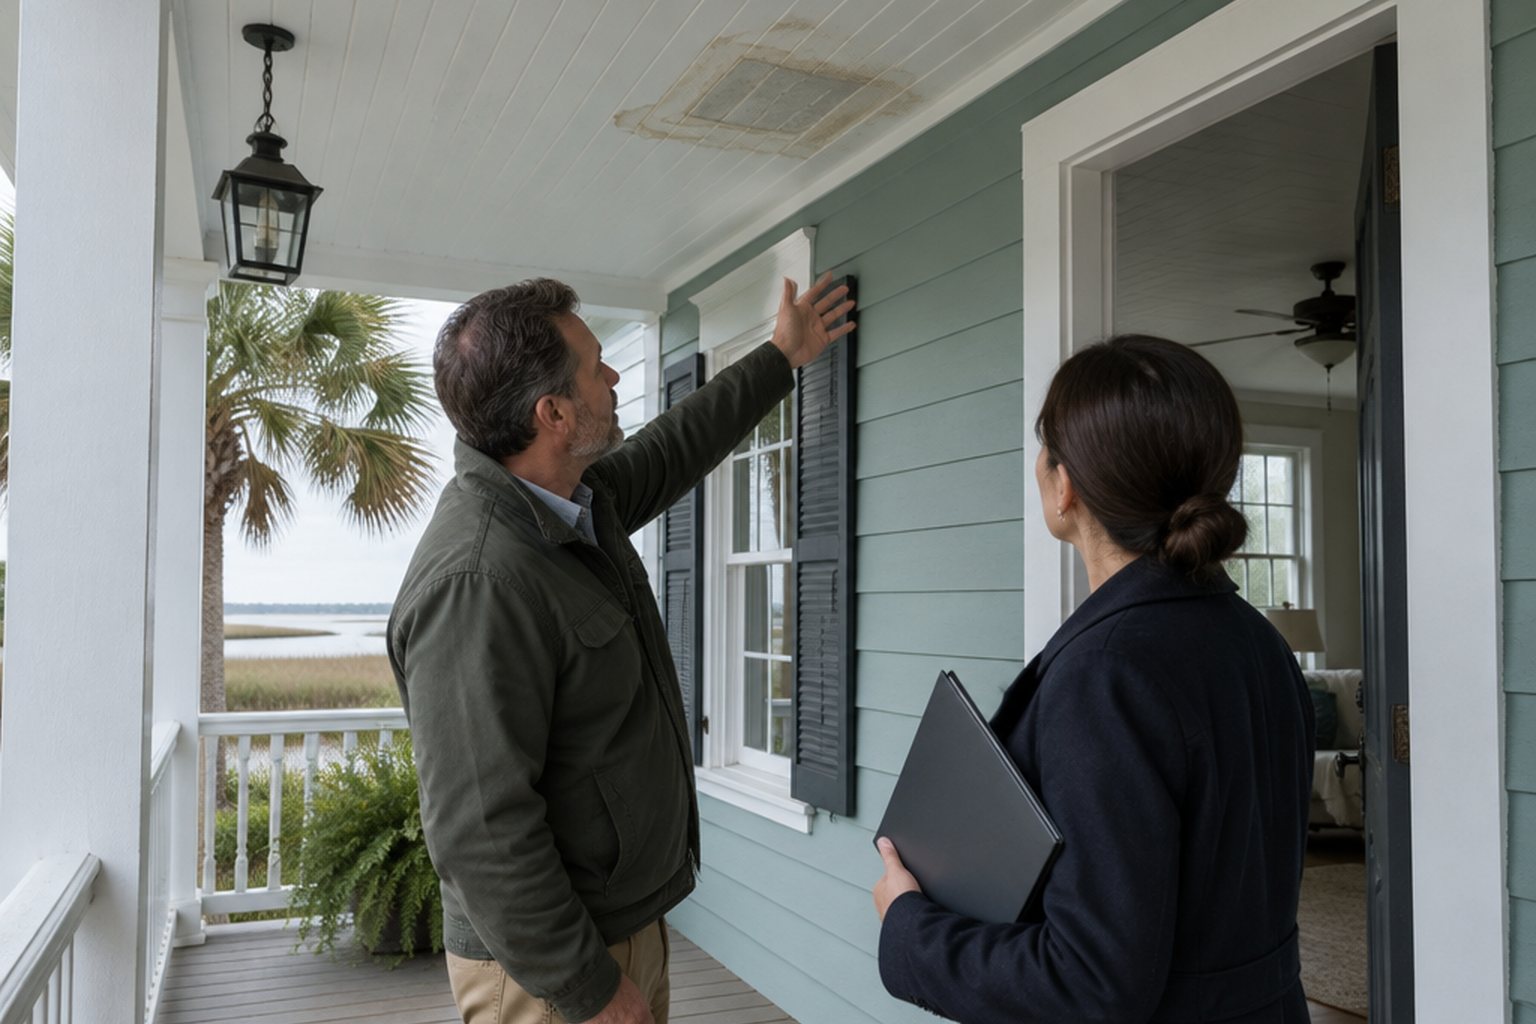
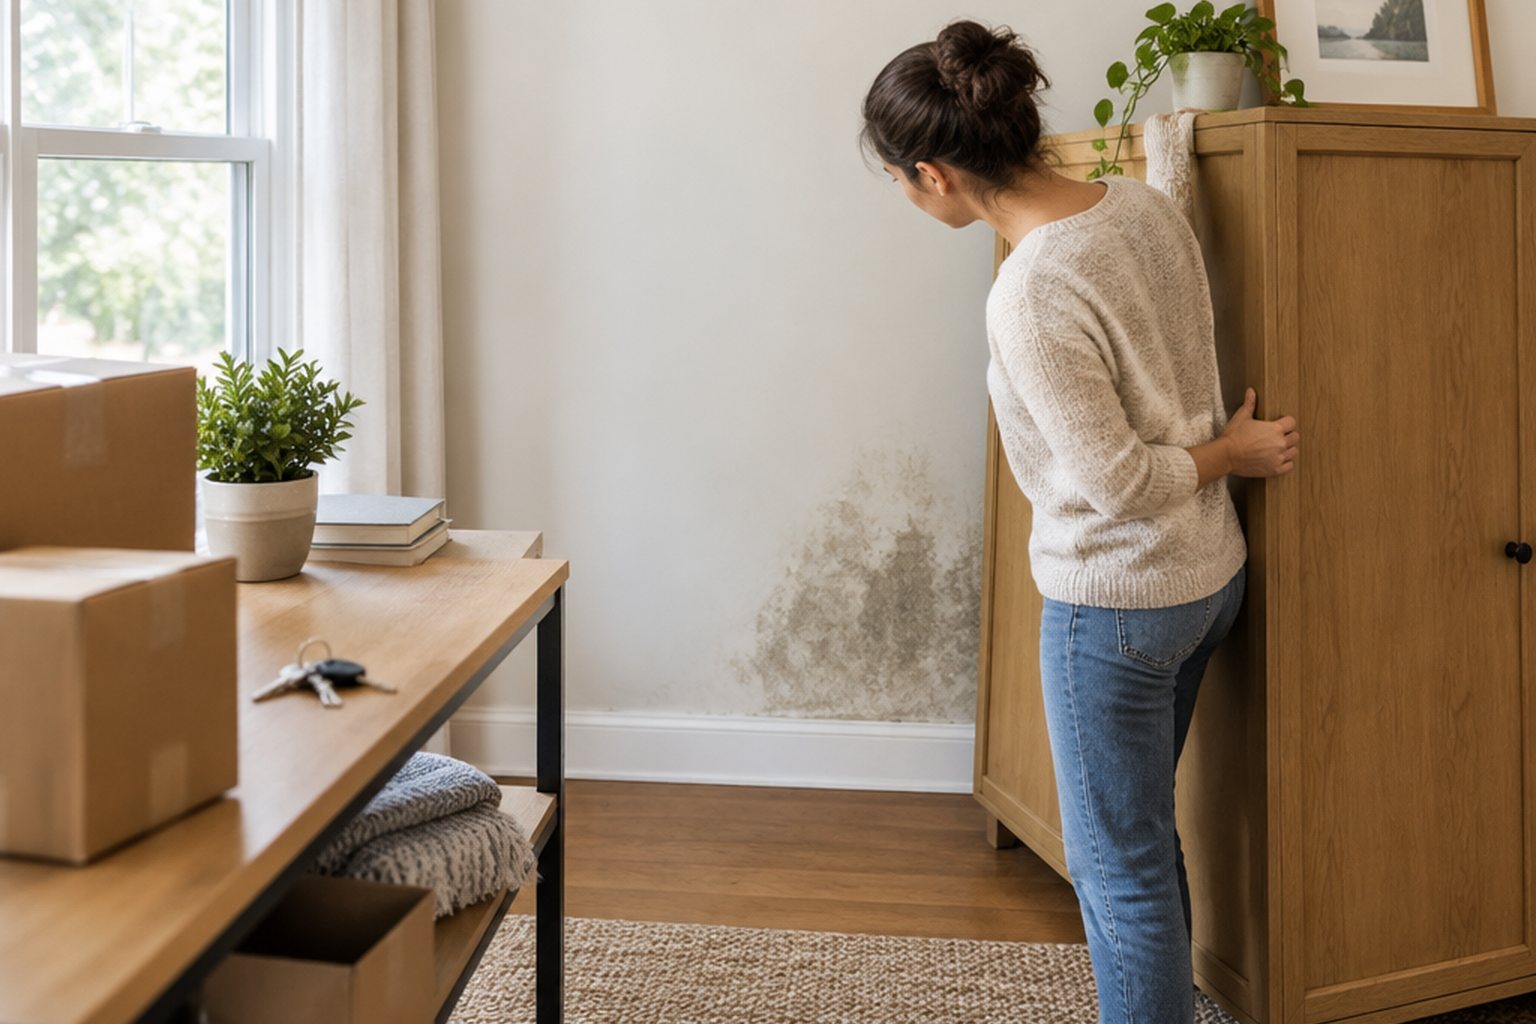
Start with the inspection finding and any needed specialist evaluation. A report describing staining, movement or an unusual installation may identify a symptom rather than the full repair. The CFPB's home-inspection guidance recommends allowing time for follow-up and discussing findings within the purchase process. Do not negotiate only around the cost of making the symptom disappear if the cause remains unknown. Separate urgent safety concerns, active damage, maintenance and discretionary improvements. The buyer and seller can then discuss a defined issue rather than comparing a vague promise to repair everything with a credit that may have no relationship to the actual work.
Understand what seller-performed repairs can accomplish
A completed repair can reduce the buyer's immediate workload and allow some verification before closing. Its usefulness depends on who defines the scope, who performs the work, which approvals apply and what evidence is delivered. A seller may reasonably want a limited, clear obligation, while the buyer may need assurance that the underlying concern is addressed. Put those expectations into the agreement through the appropriate transaction professionals. Avoid relying on a casual promise that the seller's handyman will take care of it. A repair that changes the appearance without resolving the agreed condition can leave both parties believing they fulfilled or were denied different promises.
Understand what a credit leaves with the buyer
A credit or other negotiated financial adjustment may allow the buyer to select professionals and control the later work. It can also leave the buyer responsible for investigation, coordination, permits, hidden conditions and temporary loss of use. Confirm what forms of adjustment are permitted by the transaction, financing and closing arrangements; do not assume any cash amount can be handled in any manner. Obtain advice from the relevant lender and transaction professionals. A credit is a negotiated term, not a guarantee that the resulting project will cost that amount. Evaluate whether the buyer has the time, capacity and resources to manage the uncertainty after the sale.
Compare estimates on the same repair basis
Request proposals that describe diagnosis, correction, restoration, exclusions and relevant approval responsibilities. A quote for repainting a ceiling cannot be compared directly with one that investigates a leak and restores damaged materials. Identify whether pricing is firm for a defined scope or preliminary pending access. Ask what might change the cost and which findings would trigger a revised decision. Avoid presenting one contractor's quick verbal number as a complete budget for concealed work. A useful comparison also includes scheduling and access assumptions, especially if the buyer expects to occupy the home immediately. Document uncertainty instead of hiding it inside an unexplained contingency.
Sellers should verify a repair or credit request with the same care. Request the actual inspection finding and distinguish its observation from any asserted cause. A buyer's estimate may include elective upgrades, a broader replacement scope or assumptions that have not been verified. Ask an appropriately qualified independent professional to assess the same defined condition and compare like-for-like scope, access, restoration and approval costs. Do not treat an inflated or unsupported figure as proven loss merely because it appears on a contractor letterhead. Equally, a higher price or negotiating disagreement does not establish fraud. Keep requests and responses within the transaction's communication process, preserve deadlines and ask the appropriate advisers how to document the final agreement. This protects a seller from conceding an unexplained amount while keeping legitimate defects available for a fair, evidence-based discussion.
Specify completion evidence if the seller performs work
An agreed repair provision should identify the condition, scope or required evaluation, appropriate qualifications, permits where required and records to be supplied. Decide how completion will be reviewed and what happens if necessary work is not finished on time, with advice appropriate to the contract. A receipt shows a transaction; it does not necessarily prove the technical result. For a significant issue, the relevant specialist may need to reassess the condition. Avoid asking a routine final walkthrough to certify concealed construction or specialist performance outside its purpose. Keep the agreed method proportionate to the concern so verification is both useful and realistically achievable.
Keep disclosure and repair records consistent
For South Carolina transactions, the Residential Property Condition Disclosure Act and official disclosure form provide the relevant state disclosure framework, including fact-specific provisions about knowledge and changed conditions. Do not assume that a negotiated repair automatically makes every earlier statement irrelevant or that a credit substitutes for accurate disclosure. Retain the findings, seller responses and repair documentation. If new information changes a prior statement, obtain local advice on the appropriate action. The legal effect of an update or completed repair depends on the circumstances. A clean record should explain what was known, what was agreed and what evidence supports the reported result.
Choose using timing, control and residual uncertainty
Consider the severity of the issue, available investigation time, reliability of the repair scope and each party's capacity to manage the work. Seller completion can be attractive when the task is clear and verification is feasible before closing. Buyer-managed work may be preferable when the buyer wants design control and can responsibly accept the uncertainty, subject to the transaction's terms. Neither pattern is a rule. A hypothetical roof stain with an unresolved source is different from a clearly identified missing fixture component. Evaluate whether the proposed arrangement actually answers the concern or merely moves the unresolved question to a different person after closing.
Document the final arrangement and confirm its status
Use the proper written transaction process for repair terms, credits or other adjustments. Track the applicable deadlines and do not assume negotiations automatically extend an inspection period. Preserve estimates, agreed scope, completion records and relevant approvals. If repairs are unfinished or evidence is missing near closing, consult the appropriate advisers before signing documents that describe the work as complete. For a credit, retain the repair assumptions so the first contractor visit starts from an informed brief. The best arrangement is one the parties understand and can verify, with remaining risks honestly allocated rather than hidden behind the comforting words repaired or credited.
BEFORE YOU PROCEED
Your project checklist
- Define the finding and any unresolved cause.
- Obtain comparable repair scopes with stated limits.
- Compare timing, control and remaining uncertainty.
- Confirm lender and transaction constraints on credits.
- Specify repair completion evidence when applicable.
- Document terms and preserve accurate disclosure records.
Questions that come up next
Is a repair credit always safer than seller repairs?
No. A credit can provide control while transferring cost and coordination uncertainty to the buyer. Compare the actual condition and transaction constraints.
Is a paid repair invoice enough before closing?
It may be useful evidence, but significant issues can require inspection results, specialist reassessment or other documentation appropriate to the agreed scope.
EVIDENCE & SCOPE
Sources for this guide
Applies to: US purchase planning; South Carolina disclosure law is a labeled example, contract/lender terms vary.
Reddit discussions identify questions and experiences, not verified diagnoses or code requirements. Technical claims should be read with the linked primary source, product instructions and local requirements.
- CFPB: Schedule a home inspectiongovernment
Federal home-buying guidance on independent inspection, specialist follow-up and the distinction between inspection and appraisal.
- South Carolina Code Title 27 Chapter 50: Residential Property Condition Disclosure Actgovernment
South Carolina residential disclosure statute covering applicability, exceptions, knowledge, updates and remedies subject to its conditions.
- South Carolina Residential Property Condition Disclosure Statementgovernment
Official South Carolina property disclosure form, June 2025 file, with instructions on knowledge, explanations, inspections and statutory exceptions.
- First Time Homebuyer Questions. Credits vs Asking the Seller to Repair?reddit
Buyer is unsure which inspection findings need specialist review, seller repair or negotiated credit. Only a search excerpt was available during research. Individual experiences are not legal or technical authority.
- Seller didn't make agreed upon repairs prior to closereddit
A promised garage-door repair has no receipt or completion before the buyer's final walkthrough. Full thread was available during research. Individual experiences are not legal or technical authority.